







Date Palm Country Club, Cathedral City: Home Buying Guide
Explore Date Palm Country Club homes, leased-site costs, title and financing questions, original photographs, and a practical touring worksheet.

At Date Palm Country Club, the home, its leased site and the golf-course setting need to be evaluated together. This 55+ manufactured-home community offers a different ownership and occupancy comparison from a conventional home on owned land.
Use the original photographs and practical worksheets to compare the actual home, written site costs, title, financing, inspections and intended use.
- The home and site are separate decisions. Read the actual site agreement alongside the home’s title, condition and asking price.
- Plan the full occupancy budget. Confirm incoming-buyer site costs, utilities, insurance and other required charges.
- Leased-site budget: Obtain a written incoming-buyer quote; inconsistent MLS cost fields do not verify current rent.
- Before closing: Review the site agreement, residency approval, title and transfer, financing, insurance and inspection findings.
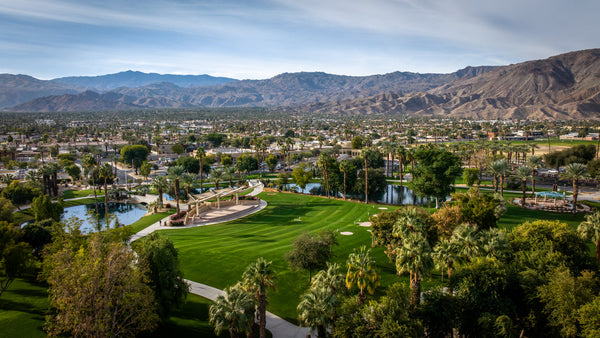
- Six original photographs: Fairways, ponds, homes and covered patios, photographed October 20, 2026.
A home purchase and a leased-site decision belong together
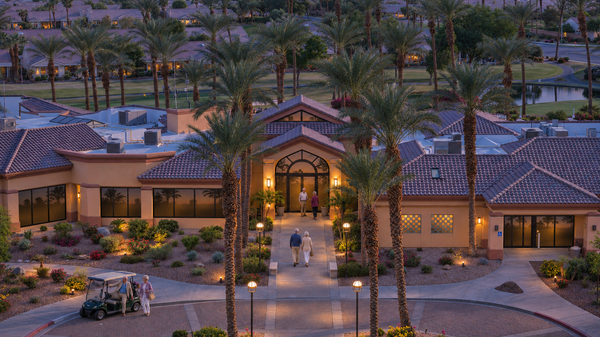
Date Palm Country Club brings low homes, covered patios, fairways and ponds together in Cathedral City. The six original October 20 photographs show how closely the residential streets and golf landscape connect. Some patios face open grass or water; others have a more enclosed street-and-neighbor relationship. The view is only one part of choosing the home.
The community operator identifies Date Palm as a gated 55+ manufactured-home community at 36200 Date Palm Drive, Cathedral City. Its advertised amenities include activities, a clubhouse, fitness facilities, swimming, tennis and spa facilities. Confirm current access, guest arrangements and any separate charges for the amenities you expect to use with community management.
For a purchase here, evaluate the home and its site agreement together. The home’s purchase price does not purchase the underlying site. Obtain the actual rental or lease agreement, its remaining term, the incoming buyer’s charges and approval requirements before treating an asking price as a complete housing budget.
This guide focuses on the Cathedral City community. Similarly named parks and conventional homes on owned land are different comparisons. Use the exact park, address and space identification when requesting records, insurance, financing or a showing.
Get an incoming-buyer space-rent quote in writing
The recurring site charge deserves as much attention as the home price. Ask management for a current written quote for the exact home, with every amount identified as monthly, annual or one-time. A listing field does not verify the incoming buyer’s rent or the terms of the actual agreement.
An association-fee field is not a complete occupancy budget. A zero or blank entry does not mean free site occupancy. Obtain an itemized statement so the same charge is not counted twice or omitted.
| Request for the exact home | Why it matters | Record before an offer |
|---|---|---|
| Incoming-buyer base site rent | The seller’s existing payment may not be the buyer’s quote. | Amount, start date, billing period and written source. |
| Additional recurring charges | Utilities, services and recreation may be billed separately. | Every mandatory charge and what the base rent includes. |
| Future adjustments | A first-year amount alone cannot describe a multiyear budget. | Adjustment formula, timing, notices and any separate assessments. |
| Lease term and renewal | MLS date fields are not the executed agreement. | Full agreement, amendments, expiration and written renewal information. |
| Transfer and approval costs | Closing and move-in may require additional steps. | Application process, required deposits and any transfer charges. |
Obtain the executed agreement and amendments for the site. Have management explain its term, expiration, renewal and transfer provisions, including any distinction between the resident agreement and an underlying land arrangement. A listing’s date field does not establish those rights.
For planning, multiply a verified monthly site charge by 12, then add the other itemized costs. Keep a second scenario for the increases allowed by the actual agreement. This is a budgeting exercise; it does not establish the enforceable rent or promise that an existing agreement transfers unchanged.
Ask about rent-control applicability rather than assuming it
Cathedral City’s mobile-home information page describes limits and exemptions involving land status, agreements and principal residence. Do not assume every Date Palm site or seasonal resident receives the same protection. Have the City Housing Office and a qualified adviser review the actual site, agreement and intended occupancy before relying on a cap or renewal assumption. This guide makes no site-specific rent-control determination.
Build the occupancy budget around your actual use
| Budget line | Evidence to obtain | How to compare homes |
|---|---|---|
| Home payment or purchase cash | Address-specific lender quote and closing estimate. | Keep loan costs separate from site rent. |
| Site rent and mandatory fees | Management’s written incoming-buyer itemization. | Use the same date and billing period for both homes. |
| Taxes or registration | Current status and outstanding amounts confirmed through transfer review. | Do not infer zero tax or registration cost from a listing slogan. |
| Insurance | A written quote for the exact unit, additions and intended use. | Compare coverage, exclusions and deductible as well as premium. |
| Utilities and services | Representative bills and the park’s billing arrangements. | Identify what is included and what is billed separately. |
| Repairs and replacements | Inspection findings and contractor estimates. | Separate immediate work from a continuing repair allowance. |
| Golf and optional recreation | Current terms for your intended activities. | Add optional spending after the mandatory housing total. |
A seasonal home still incurs continuing costs while vacant. Ask who handles a water leak, equipment failure or exterior issue when you are away. Review insurance conditions for vacancy and the practical arrangements for checking the property, with management approval where needed. Use your expected occupancy rather than copying the seller’s pattern.
Separate the cash needed to close from the amount needed to live there. A purchase that leaves no room for an aging cooling system, roof work or uncovered repair may be difficult to sustain even if the asking price is within reach. Compare two homes using the same repair assumptions and the same period of occupancy.
Review title and financing before relying on a loan plan
The home’s title and tax or registration status determine which transfer instructions apply. HCD publishes separate private-sale instructions for homes on local property tax and homes on yearly registration, including different ownership documents. Start with HCD’s transfer instructions and have the transaction professionals identify the correct route for the actual home.
Request the ownership and registration records, matching unit identifiers, lien information and confirmation of any amounts needed for transfer. Have discrepancies between documents, the home and the listing resolved before closing. A listing address or a seller’s statement alone is insufficient evidence of transferable title.
Land ownership and whether a manufactured home is titled as personal or real property affect financing, as the CFPB’s manufactured-housing finance research explains. This 2021 report is background on the distinction, not a current rate quote. Ask a lender familiar with homes in leased-site parks to review the exact unit, construction year, title and agreement before building your budget around a particular loan.
Get the proposed payment, term, down payment, fees and any conditions in writing. Ask what the lender still needs to verify and whether the approval is for this home or only an initial borrower review. Park residency approval and lender approval are separate questions to resolve on the purchase timeline.
Do not use an MLS financing label or foundation-related field as a loan approval. Have the intended lender review the specific home, title documents, construction and site agreement before relying on a financing plan.
Look beneath the improvements and outside the living room
An updated kitchen can coexist with older equipment, wiring, plumbing or an unresolved alteration. Use an inspector familiar with manufactured homes and bring in specialists where the findings warrant it.
| Inspection focus | Look for and ask about | Follow-up evidence |
|---|---|---|
| Roof and ceilings | Leaks, staining, roof transitions and past repairs. | Roof assessment, invoices and replacement estimate where needed. |
| Support and under-home area | Movement, moisture, plumbing access and visible deterioration. | Qualified inspection of supports, connections and identified defects. |
| Heating and cooling | Equipment age, operation, distribution and service access. | Service records, performance review and replacement planning. |
| Electrical and plumbing | Altered circuits, supply lines, shutoffs and visible repair history. | Specialist evaluation and permit records for relevant work. |
| Patios, enclosures and carports | How added structures connect to the home and drain. | Approved plans, permits and final inspection records. |
| Windows, doors and floors | Operation, unevenness, water intrusion and transitions. | Determine the cause of defects before choosing cosmetic repairs. |
HCD’s modification and alteration guidance explains permitting requirements for changes to manufactured homes. Ask HCD and the appropriate local agency which records and approvals apply to the home, accessory structures and site work. Management permission, a contractor invoice and a final permit inspection answer different questions; collect the relevant records for the improvements you are buying.
Walk the patio, parking area and side access with the same care as the interior. Note changes in surface level, drainage paths, access to service equipment and the route from the car into the house. Revisit if the first showing does not let you assess the features important to your daily use.
Verify residency, guest and golf arrangements separately
Ask management for the current age-qualification and residency rules for every intended occupant, along with application requirements and timing. Do not infer that each household member must meet the same age threshold or that a guest can remain indefinitely. Confirm the written rules rather than relying on an MLS flag.
Put your intended use into the review: full-time residence, winter visits, extended guests, pets, more than one vehicle or a need for RV storage. Request the applicable limits and charges. Confirm proposed rental activity and any planned exterior changes in writing before counting on either. This guide does not verify rental permission for a particular home.
The golf operation describes an executive 18-hole, par-58 course designed by Ted Robinson, with 3,100 yards from its longest tees. Review the official course information and arrange a round if golf is central to your plans. Playing the course and buying a home are separate decisions.
Confirm current tee-time access, resident options, guest costs and any membership conditions directly with the golf operation. The membership page reviewed for this guide is labeled 2024/2025, so its posted prices are not presented as current 2026 rates. A golf-course view does not establish included play or a right to use every facility.
For a specific site, sit outside at different times and listen for course activity, maintenance equipment, road traffic and neighboring uses. Look at afternoon exposure, shade and privacy from the rooms you use most. The photographs help you choose questions for a visit; they cannot measure sound, comfort or seasonal conditions.
Take the same comparison sheet to each home
| Item | Home A | Home B |
|---|---|---|
| Home price and current status | Date, source and terms. | Date, source and terms. |
| Site charge and lease | Written buyer quote; agreement and remaining term. | Written buyer quote; agreement and remaining term. |
| Title and transfer | Unit identifiers, owners, liens and transfer route. | Unit identifiers, owners, liens and transfer route. |
| Financing and insurance | Quotes for this exact unit and use. | Quotes for this exact unit and use. |
| Comparable closed homes | Match size, age, condition and site features. | Match size, age, condition and site features. |
| Immediate work and later repairs | Inspection findings and written estimates. | Inspection findings and written estimates. |
| Approvals and intended use | Residency, guests, pets, parking and alterations. | Residency, guests, pets, parking and alterations. |
| Complete recurring total | Mandatory costs first; golf and optional use separately. | Mandatory costs first; golf and optional use separately. |
After each visit, mark what you observed, what you have in writing and what remains unresolved. Return to the strongest home with the inspection findings and complete cost information. That makes the choice about a workable home and occupancy arrangement, with the view and amenities weighed alongside their actual costs.
Compare Date Palm Country Club homes with Mark Miller
Bring your preferred layout, intended occupancy, outdoor-space priorities and comfortable total monthly budget. I can help compare the available homes with the closed-sale evidence and organize the questions for management, the lender, inspectors and the transfer professionals.
For other community and ownership comparisons, explore the Coachella Valley Community Explorer. Confirm current availability and property-specific terms before arranging a visit.
Questions buyers ask
Is Date Palm Country Club a 55+ community?
The community operator markets Date Palm as 55+. Obtain the current written residency and age-qualification requirements for every intended occupant, together with management application requirements and timing.
Does a low home price mean a low total monthly cost?
The purchase price is only one part of the budget. Obtain the incoming-buyer site-rent quote, mandatory fees, utilities, insurance, tax or registration status, repair estimates and financing terms. Keep optional golf spending separate.
What is the current space rent?
Request a current written, itemized quote for the exact home from management. Confirm which charges are monthly, annual or one-time and review future adjustments in the actual site agreement. Listing fields do not establish the incoming buyer’s rent.
How do I confirm the site agreement’s term?
Obtain the executed agreement and amendments for the site. Confirm expiration, renewal and transfer provisions, and the relationship between the resident agreement and any underlying land arrangement. An MLS date field does not establish those rights.
Can I use a standard home loan?
Have a lender experienced with leased-site manufactured homes review the exact unit, title, construction year and site agreement. Financing eligibility and terms require property-specific confirmation; an initial borrower review or an MLS label does not settle them.
Is golf included with the home?
Do not assume the home purchase or site charge includes golf. Confirm present resident options, eligibility, guest rules, tee times and costs with the golf operation.
Sources and ownership references
- Official Date Palm community operator for location, 55+ marketing and advertised amenities. Current household rules, costs and availability require direct confirmation.
- Official Date Palm course details and membership page. Confirm current resident access and membership terms directly with the operator.
- City of Cathedral City mobile-home resources for a starting point on rent-control applicability and exclusions. No site-specific legal determination is made.
- California HCD transfer instructions and manufactured-home alterations and permits. Use the route and approvals applicable to the actual unit and work.
- CFPB manufactured-housing finance research, May 27, 2021. Background on land/title and loan distinctions, rather than present rates or a loan approval.
- DOI Date Palm photo profile; Cathedral City housing market; Community Explorer. Six original photographs by Mark Miller, October 20, 2026.


